Hail season in Lubbock is not a question of if, but when. When a West Texas storm rolls through and pelts your roof with ice, the damage isn’t always obvious from the ground, but it can quietly shorten your roof’s life by years and lead to leaks long after the sky clears. This 2026 guide walks Lubbock homeowners through exactly what to do after a hailstorm: how to spot the damage, how the insurance claim process really works, what your policy will and won’t cover, and how to avoid the storm-chasing contractors who flood town after every big event.
Here is how hail damage roof repair actually works in Lubbock: what the damage looks like, how the claim runs, and how to avoid the crews that follow the storm in.
On this page, a complete guide to hail damage roof repair in Lubbock, TX:
- Quick Answer: Hail Damage Roof Repair in Lubbock
- How the Hail Insurance Claim Process Works in Lubbock
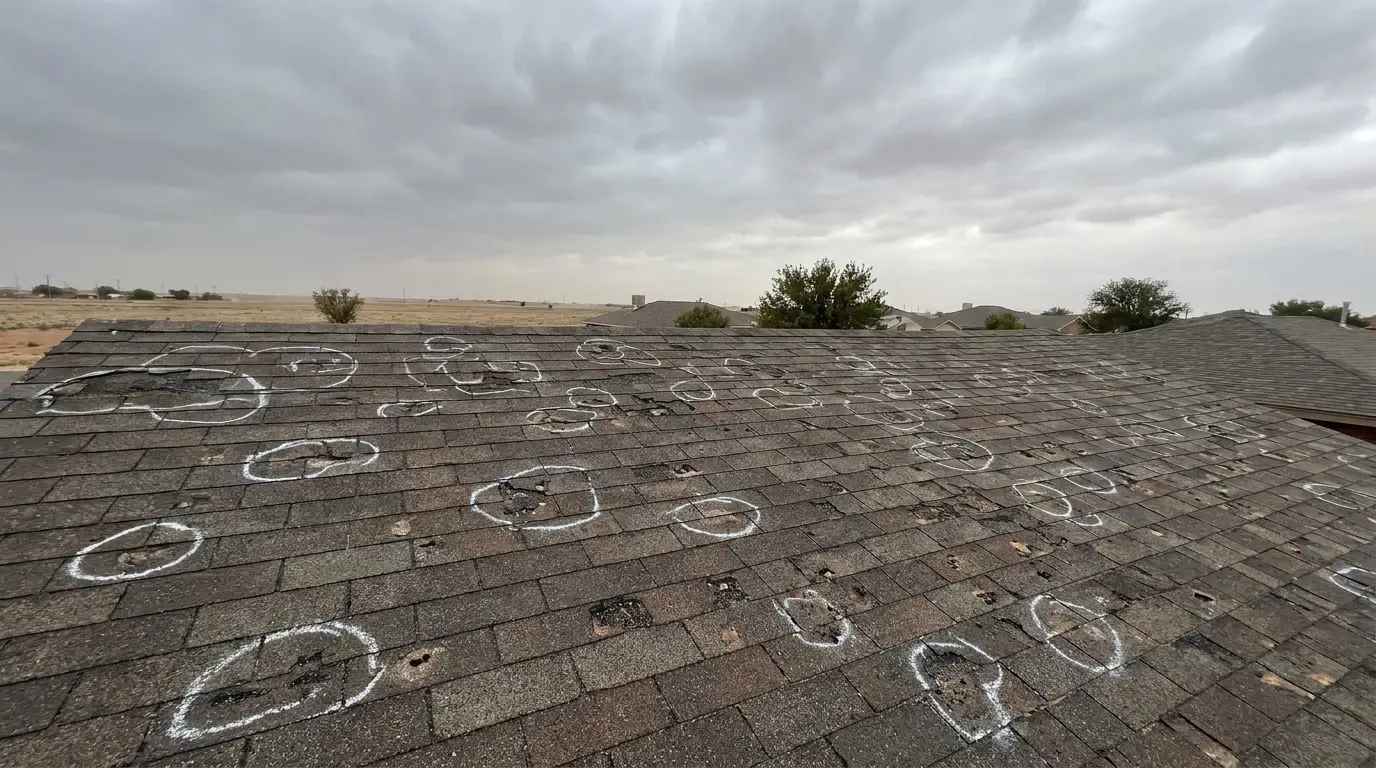
- What Hail Damage Actually Looks Like
- Lubbock Realities: Deductibles, Storm Chasers, and Timing
- Repair vs. Replace: What Insurance Will Cover
- Final Word: Move Fast, Document Everything, Hire Local
- Frequently Asked Questions About Hail Damage Roof Repair in Lubbock
Quick Answer: Hail Damage Roof Repair in Lubbock
Act within days, not months. After a hailstorm: (1) document the storm date and take photos of any visible damage, (2) get a free professional roof inspection before you call your insurer, (3) file your claim promptly: most Texas policies require it within a reasonable time, often one year, and (4) choose a licensed local roofer, not an out-of-town storm chaser. A legitimate hail claim can cover most or all of a roof replacement, minus your wind/hail deductible.
The biggest mistakes we see in Lubbock are waiting too long to file and letting a door-knocking storm chaser inspect the roof first. Hail damage is time-sensitive: insurers can deny claims filed long after the storm, arguing the damage is old or from wear. If you’re not sure whether your roof was hit, a no-cost inspection is the safest first move, schedule one here.
How the Hail Insurance Claim Process Works in Lubbock
Filing a roof claim feels intimidating, but it follows a predictable path. Here’s the sequence we guide Lubbock homeowners through:
- 1. Get an independent inspection. A licensed roofer documents hail hits, granule loss, and collateral damage (gutters, screens, AC fins) that proves the storm’s severity.
- 2. File your claim. Report the date of loss and provide your documentation. Your insurer assigns an adjuster.
- 3. Meet the adjuster on-site. Your roofer should be present to make sure all legitimate damage is counted, adjusters miss things.
- 4. Review the scope and payout. The insurer issues an estimate based on replacement cost, minus depreciation and your deductible.
- 5. Complete the work and recover depreciation. Once the job is done, you submit final invoices to release the withheld (recoverable) depreciation.
Most policies pay in the “two-check” system: the first check is the Actual Cash Value (replacement cost minus depreciation and your deductible), and the second releases the recoverable depreciation after the work is finished and documented. Understanding this up front prevents the panic of thinking a claim is underpaid when it simply hasn’t fully paid out yet.
What Hail Damage Actually Looks Like
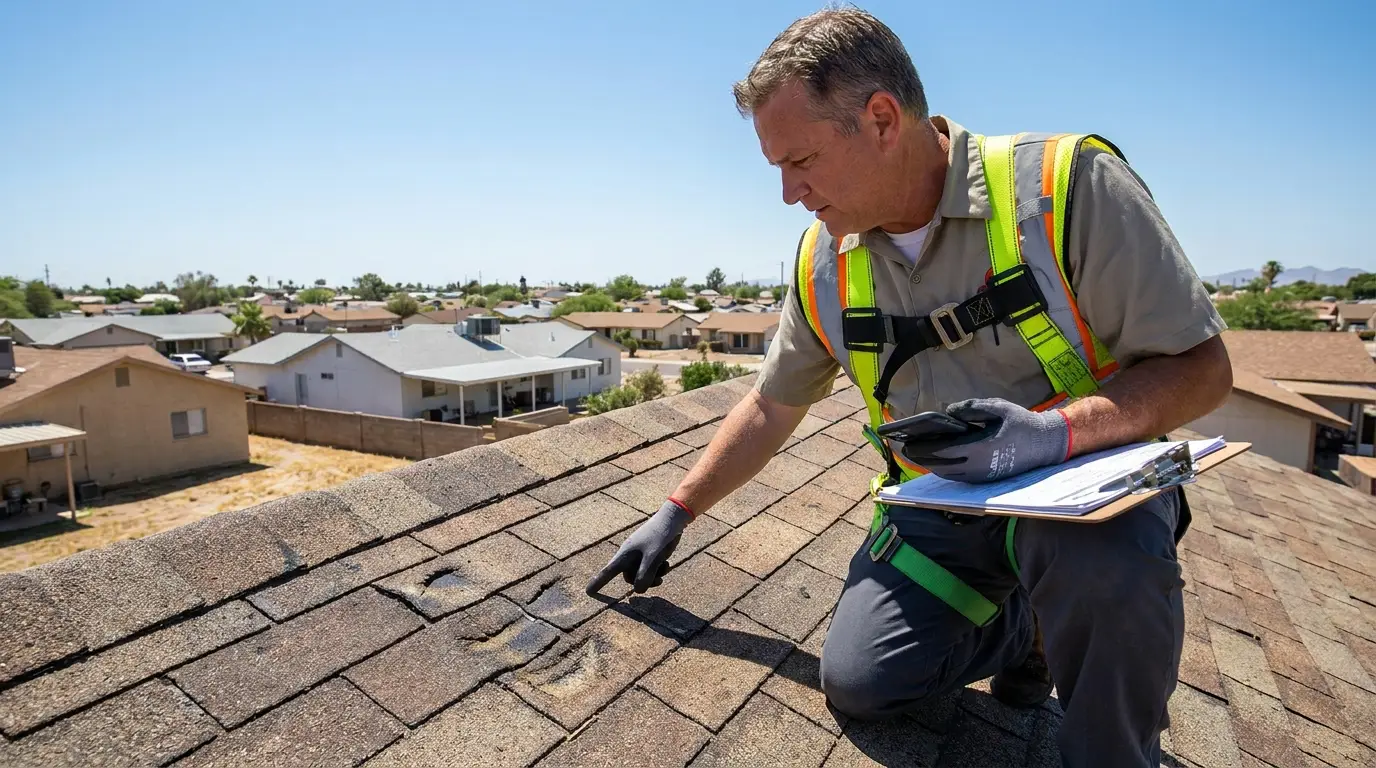
Homeowners often assume that if the roof isn’t leaking, it’s fine. Hail damage is usually subtle at first, here’s what inspectors look for:
Bruises and Soft Spots
Hail knocks the protective granules off asphalt shingles and bruises the mat underneath. These soft, dark spots aren’t always visible from the ground but expose the shingle to UV and accelerate failure.
Granule Loss in Gutters
Piles of sand-like granules in your gutters or at downspout splash blocks are a classic sign your shingles took a beating.
Collateral Damage
Dented gutters, downspouts, window screens, garage doors, and AC condenser fins all corroborate a hail event and help prove the storm’s intensity to your adjuster.
Cracked or Missing Shingles
Larger hail can crack shingles outright or knock them loose, which leads directly to leaks. If you see any of these signs, review our guide to the signs you need a new roof in Lubbock.
Lubbock Realities: Deductibles, Storm Chasers, and Timing
West Texas has its own claim landscape, and knowing it protects your wallet.
The rules here are public. The Texas Department of Insurance sets out how storm claims, deductibles and appraisal work in Texas, and the NOAA Storm Prediction Center keeps the severe-weather record that tells you whether a storm actually crossed your address.
Separate Wind and Hail Deductibles
Many Texas policies now carry a separate wind/hail deductible of 1% to 5% of your dwelling coverage, not a flat dollar amount. On a $350,000 home, a 2% deductible means $7,000 out of pocket before insurance pays a cent. Always read your declarations page before assuming a claim is worth filing.
Beware Out-of-Town Storm Chasers
After every major Lubbock hail event, out-of-state crews swarm neighborhoods knocking on doors. They collect insurance money, do fast work, and vanish, leaving you with no local warranty support. Choose an established local company you can find again next year.
Timing Matters for Hail Damage Roof Repair
File promptly. Insurers scrutinize late claims and may argue the damage predates the storm or resulted from wear rather than a covered event. The clock starts on the date of the storm.
Repair vs. Replace: What Insurance Will Cover
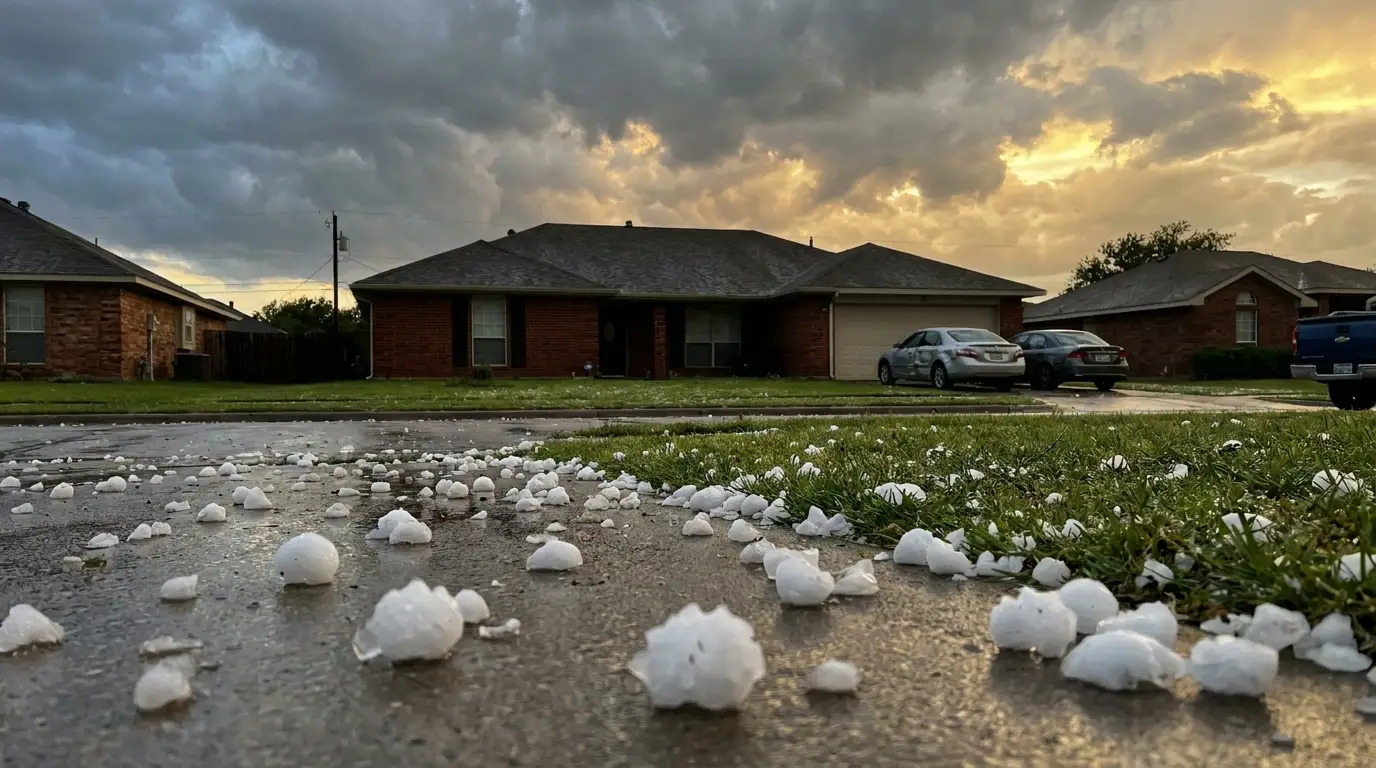
Insurance generally covers hail damage as a sudden, covered peril, but whether you get a repair or a full replacement depends on severity. Scattered damage on one slope may be repaired; widespread bruising across the roof usually justifies replacement, especially when matching discontinued shingles is impossible. If your roof is being replaced anyway, it’s the perfect time to consider upgrading to a more durable material, many homeowners put their claim toward the cost difference of a hail-resistant metal roof. For a full breakdown of replacement pricing, see our Lubbock roof replacement cost guide.
Final Word: Move Fast, Document Everything, Hire Local
A hail claim done right can restore your roof for little more than your deductible: but only if you move quickly, document thoroughly, and put a knowledgeable local roofer in your corner before the adjuster arrives. Elite Roofing and Exterior has walked countless Lubbock homeowners through the hail-claim process from inspection to final depreciation check. If a storm just came through, don’t wait for a leak. Explore our roofing services or call (806) 451-3393 for a free, no-obligation hail inspection.
Frequently Asked Questions About Hail Damage Roof Repair in Lubbock
Quick answers to what Lubbock homeowners ask most about hail damage roof repair
Most Texas homeowner policies require you to file within a reasonable time after the date of loss, and many set a hard deadline of about one year. The sooner you file, the stronger your claim, late claims are often disputed or denied because insurers argue the damage is old. Check your policy's specific deadline and act promptly after any significant Lubbock hailstorm.
Hail is typically classified as an “act of God” rather than driver fault, so a single weather claim usually affects your individual rate less than an at-fault claim would. However, rates across all of West Texas tend to rise after major storm seasons regardless of whether you file. Not filing a legitimate claim leaves you paying premiums for coverage you never use while your roof deteriorates.
Before. An independent inspection tells you whether you actually have claimable damage and gives you documentation to support the claim. Calling your insurer first without knowing the extent of the damage can lead to a lowball scope or a denied claim. A reputable local roofer will inspect for free and tell you honestly whether filing makes sense.
It's a separate deductible that applies only to wind and hail claims, common on Texas policies. Instead of a flat dollar amount, it's usually 1% to 5% of your home's dwelling coverage. On a $300,000 home, a 2% wind/hail deductible is $6,000, which you pay before insurance contributes. Always confirm your exact figure on your declarations page.
Generally, no. Out-of-town storm-chasing crews flood Lubbock after big hail events, do rushed work, and leave with no local presence to honor a warranty. Choose an established, licensed local roofer with a physical Lubbock presence and verifiable reviews so you have someone to call if an issue arises years later.